The 10-year minus 3-month spread is 0.83 points and positive for 250 sessions, versus 1.89 points inverted on Jun 1, 2023
Jurrien Timmer says the Fed is effectively 'uncutting' its insurance cuts and he doesn't call it a true tightening cycle. The curve supports him: the 10-year minus 3-month spread has been positive for 250 straight sessions and sits at 0.83 points today. On Jun 1, 2023 it hit 1.89 points inverted, the deepest since 2000.
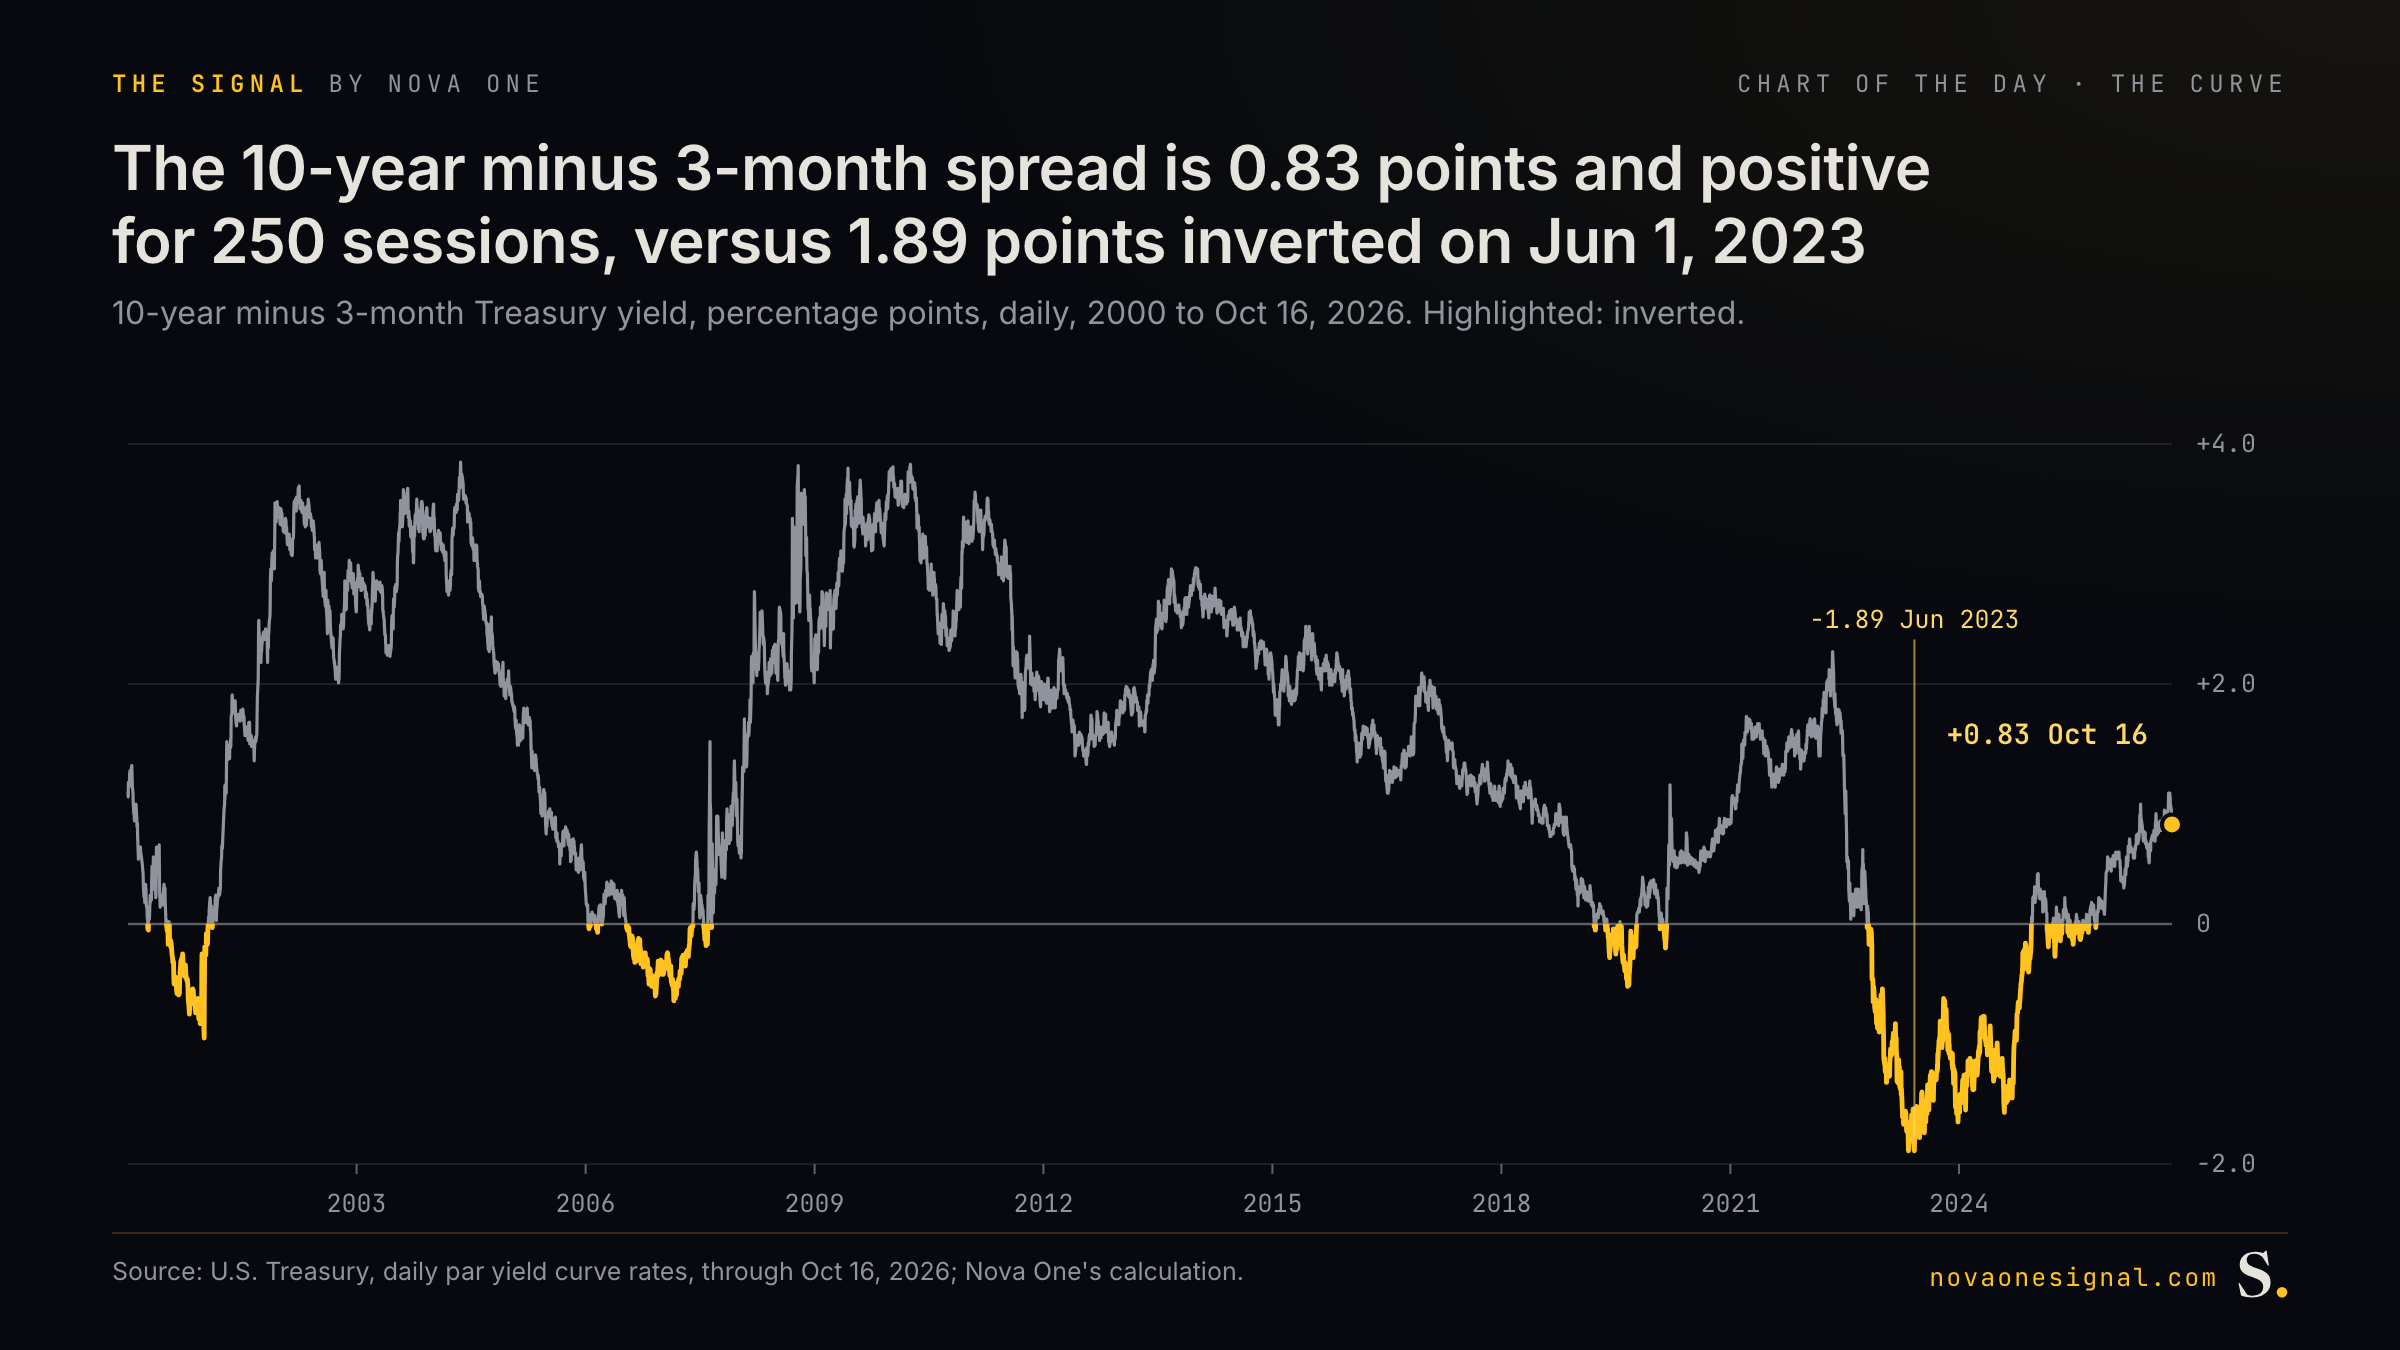
The 10-year Treasury yield minus the 3-month yield, every trading day since 2000. Above zero is a normal curve: lending long pays more than lending short. Below zero, highlighted, the curve is inverted, a classic warning sign bond investors watch.
The 3-month yield closely follows the Fed's policy rate, so this spread works as a running check on whether policy is tight enough to bite. With 0.83 points of cushion, zero is the line to watch, and a drop back below it would test Timmer's 'uncutting' read.
Timmer: the Fed is effectively 'uncutting' its insurance cuts, which he does not call a true tightening cycle.
The Compound and Friends, Jurrien TimmerSpread now 0.83 points, positive. 250 consecutive positive sessions. Deepest inversion since 2000: 1.89 points on Jun 1, 2023.
A true tightening cycle inverts this spread. This one hasn't, which fits Timmer's read.
Get The Signal by email
Two letters a week: a Mid-Week Check-In on Wednesdays and a Week in Review on Saturdays.
We use your address only to send The Signal. Unsubscribe any time. Privacy
Source: U.S. Treasury, daily par yield curve rates, through Oct 16, 2026; Nova One's calculation. Every number on the chart is computed from the source data in the same run that drew it. The Signal is research, not investment advice. How we work · Disclosures